Instant Claim Payments Only Help If the Claimant Can Actually Use Them
Providers can now deliver a claim payment within minutes. For claims teams, the differences that matter are who chooses the payout method and what reports back after the payment is sent.
A total loss is approved on a Friday afternoon. Within the hour, the carrier’s payment rules send the claimant a virtual card by email, because that is the default method for this type of claim. On Monday morning the claimant calls. They wanted the money in their checking account, and the email they did not recognize is still unopened in a spam folder.
Now the adjuster is spending part of Monday on a payment question instead of a claim. Repeat that across a week of claims, and the cost shows up in support calls, reissues and manual follow-up. The payment that left first can still be the last one closed.
What kinds of providers do insurers use for instant claim payments?
Many insurers buy this capability from one or more of four kinds of provider. They are not interchangeable, and the right choice depends on where the gap sits in your current claims and payment systems.
- Insurance payment networks. These connect carriers and payees on both sides of a payment. Their main advantage is reach, and the trade-off is adopting the network’s model of how payments work.
- Payments embedded in a P&C core platform. Disbursement is a capability of the core system, which suits a carrier that runs that core and wants payments inside the same contract. It is a harder fit for a carrier that operates several policy administration systems.
- Claims treasury and settlement infrastructure. The focus is moving and settling funds, including real-time settlement and multi-currency needs, so this model is strongest where treasury is the gap.
- Disbursement platforms alongside the core. These sit beside the claims and policy systems you already run and handle payee communication, payout choice and status. They are worth a look when the core is staying and the payout experience is what needs to change.
Our guide to the leading providers in 2026 names companies in each category.
Providers can reach the same two public instant rails, FedNow (operated by the Federal Reserve) and the RTP network (operated by The Clearing House), so rail access alone often does not separate one provider from another. Instant rails also move the point at which controls such as payee verification have to happen, which our article on how carriers pay claimants after approval covers in detail.
What does “multiple payout options” actually mean?
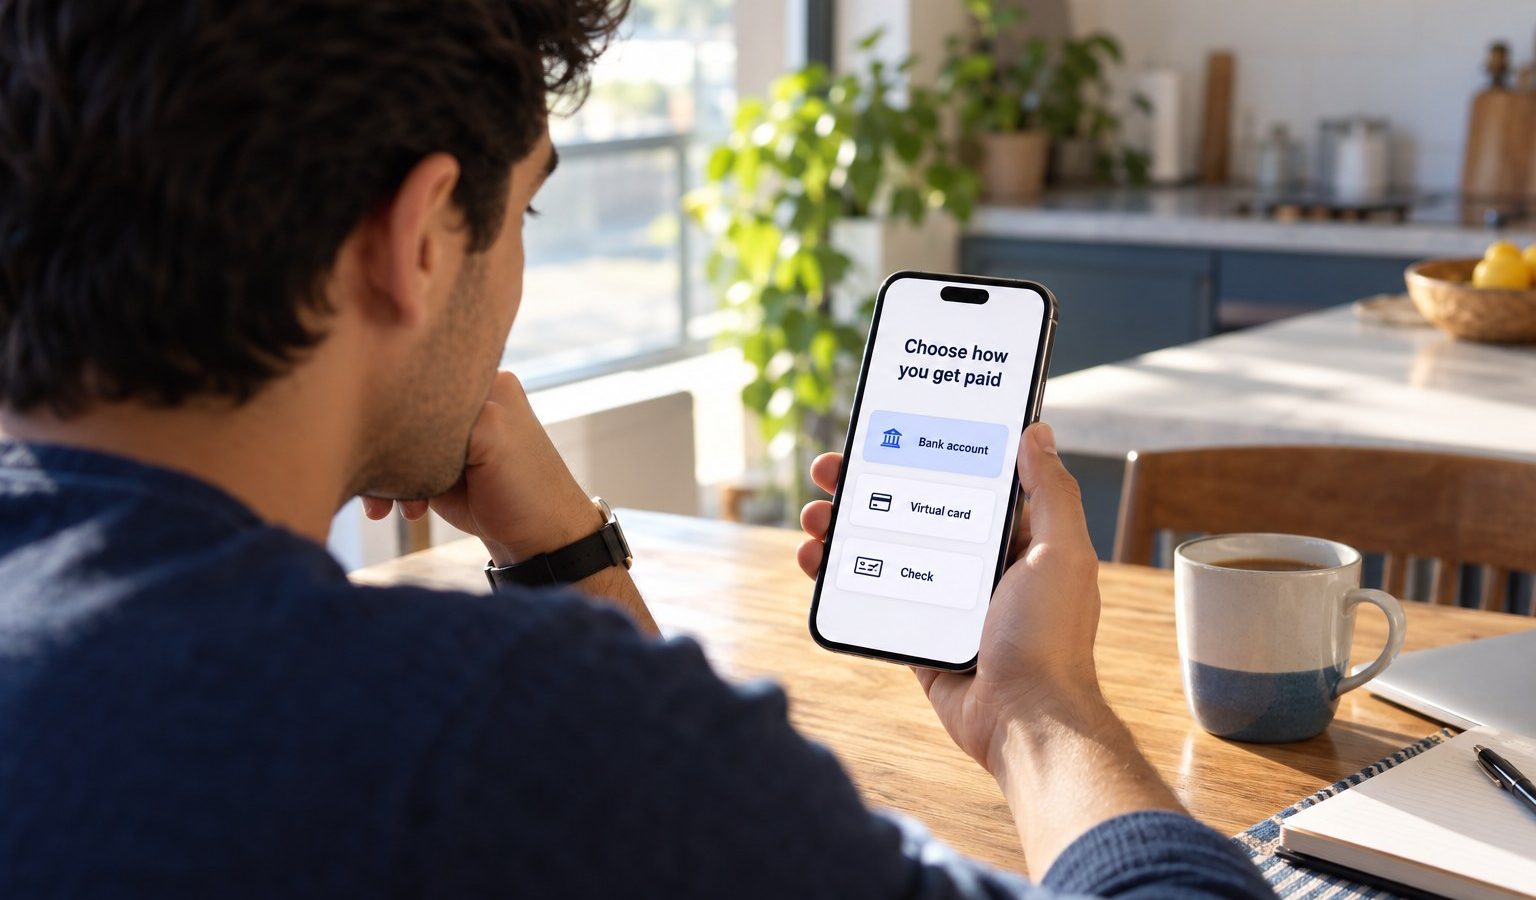
The phrase is used in two different ways. It can mean a provider supports several rails and picks one for the payee by rule, or it can mean the payee is shown the options the carrier permits and chooses one.
Consider three payees in one week of claims. A homeowner with a roof replacement claim has a checking account and wants the money there. A roofing contractor owed a reimbursement wants it in the account the business already uses. A policyholder staying with relatives after a fire has no stable mailing address and may prefer another option entirely. A rule cannot know any of this, but the payee does.
Payee choice does not mean forcing electronic payments on anyone. The carrier decides which options are available, and the payee chooses among them. For some payees and some settlements, a paper check is the right answer. Offering a choice also tends to reduce status calls, because the payee picked a method they already know how to use.
What has to be true for “instant” to mean anything operationally?
Delivery speed is the part the rails already handle. Three things decide whether a payment that arrives promptly also works for the payee, and each one can be tested in a live demonstration.
- Who chooses the method. Ask to see what the payee sees. If the screen shows the options you permit and lets the payee pick, the choice is real. If a rules engine sets the method before the payee is ever contacted, it is not.
- What reports back. Status changes should reach the claims system as they happen, including which method the payee selected, instead of arriving in a file the next day. When they do, the adjuster and finance see the same status, there are usually fewer support calls, and reconciliation needs less manual matching.
- What happens to exceptions. Returned ACH, a wrong account number, an address correction and a lost check are routine in any claims operation. Ask the provider to stop a payment and reissue it on the payee’s preferred method without starting a new payment from scratch. Without that, each exception becomes a manual case for the adjuster or the finance team.
This is also why a fee schedule is a poor way to compare providers. As we set out in What an Outbound Claim Payment Actually Costs, the larger cost usually sits in the work around each payment, so judge any provider on total operational cost.
What about payments that involve more than one payee?
Some claims stop being simple. An auto total loss can split into a lienholder payoff, the claimant’s remaining balance and a payment to a body shop, while a property claim may need the mortgage company named on the payment. Each of those payees has a different need, a different preferred method and a different timeline.
A process built around a single rail can break here. The claims system needs the status of each leg, plus a clear signal when the claim payment as a whole has settled. Finance needs funds tracked by line of business so that tie-out does not depend on a spreadsheet. Where a two-party check is still required, the right form depends on the parties, and a provider should be able to explain which forms it supports.
Where DisburseCloud fits
DisburseCloud is a payment orchestration platform for outbound claim payments. It is not a bank, a payment processor, a claims system or a policy administration platform. It is designed to connect to the claims and policy systems a carrier already runs.
The carrier configures which payout options are available, and the payee chooses from them. As payment events occur, webhooks can update the carrier’s downstream systems automatically, which can reduce manual reconciliation. DisburseCloud has a SOC 2 report, available to prospective customers under NDA.
This is not the right fit for every organization. A carrier on a single core with embedded payments, or one already inside a payment network, may be well served by those models. DisburseCloud is most relevant when the core is staying and the payout experience is the gap, and implementation depends on your existing systems, workflows and business requirements.
What should you ask any provider?
These questions apply to every provider in the category, including us. Start with the three tests above: who chooses the method, what reports back, and what happens to exceptions. Then ask the questions below, and ask to see each answer in a live demonstration rather than on a roadmap.
- Reconciliation. Does payment status close against the claim record automatically, or does finance still match payments by hand?
- Multi-party claims. Can each payee on one claim be tracked separately and the claim settled as a whole?
- Payee support. Who answers payee questions, and in which languages?
- Security. Which certifications or audit reports, such as SOC 2, are actually held, and can we see the report itself rather than a badge?
- Implementation. Which of our systems does it connect to, and what does scoping involve?
A provider that answers these clearly is more likely to reduce the follow-up work that comes after even a prompt payment.
To see how payee choice and status reporting could work in your claims operation, talk with our team.
Sources
How Insurance Carriers Pay Claimants After a Claim Is Approved (August 6, 2026)
What an Outbound Claim Payment Actually Costs (August 18, 2026)
Federal Reserve Board: FedNow Service
The Clearing House: Real-Time Payments (RTP network)
Nothing in this article is legal, tax, or regulatory advice.