Claims Vendor Payment System Design: Paying Claimant, Contractor, and Mortgagee From One Instruction
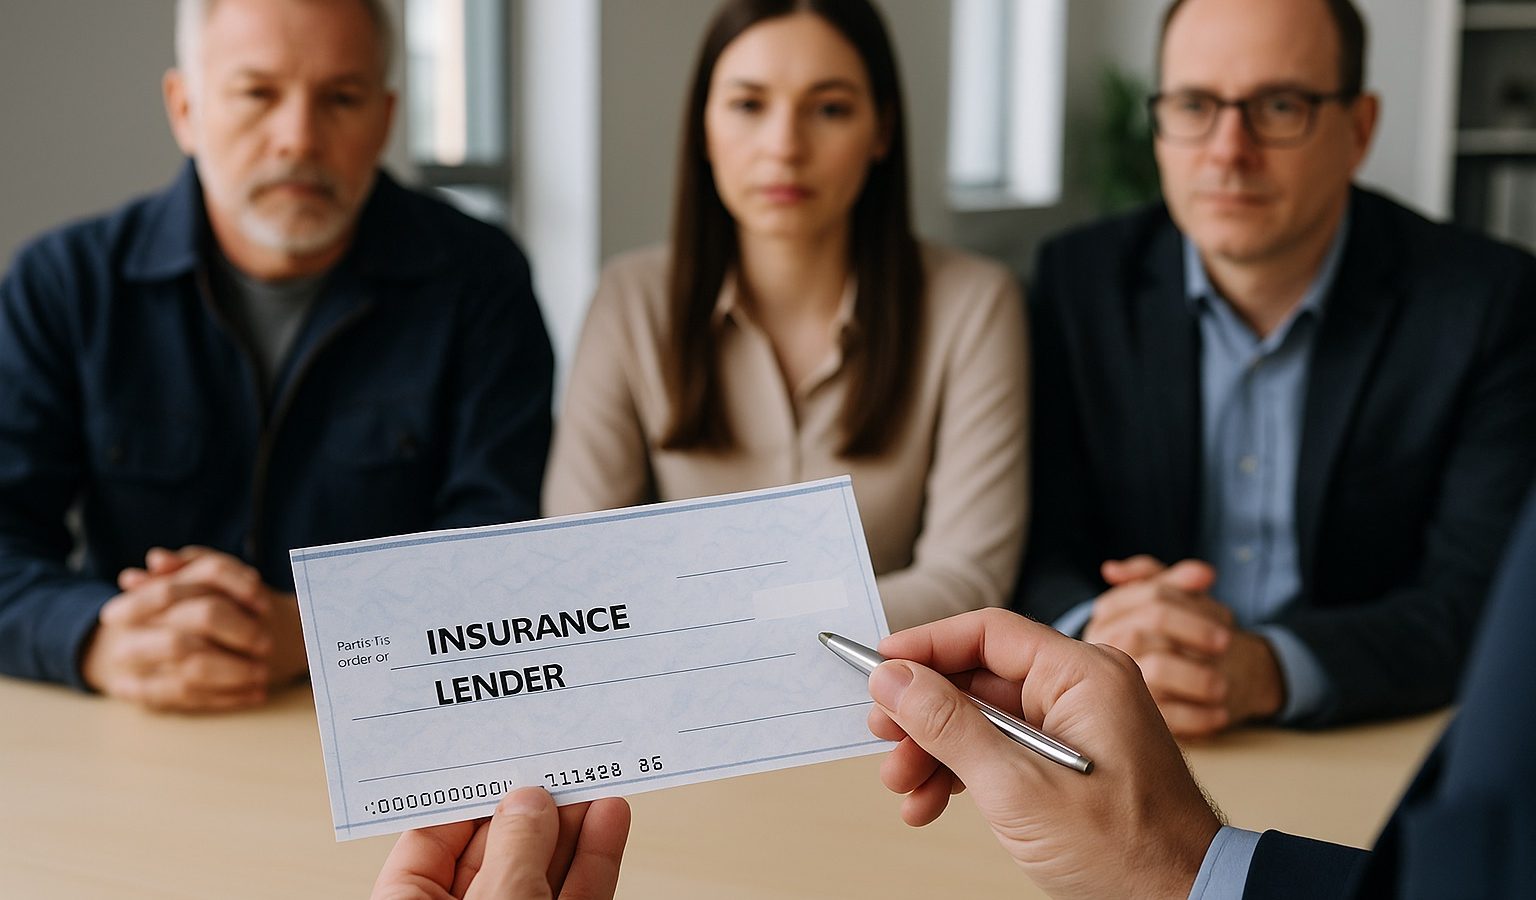
A property claim with a mortgage attached can involve three separate parties waiting on the same check, and that check can only be in one place at a time. One loss event, three coordinated payments, each one gated by the slowest party in the chain.
Most of those claims still move through a check with two names on it: the insurer and the lender. Both have to sign it. It gets mailed out, signed by hand, and deposited, all as physical steps. Add a contractor waiting on draw payments and a claimant waiting on the balance, and the gate becomes structural. Every day the check sits, in a mail tray, on a signing desk, in an inbox waiting on a signature, is another day the promise the carrier already made hasn’t been kept.
The cost is measurable. J.D. Power’s 2025 U.S. Property Claims Satisfaction Study put average repair-completion cycle time at 32.4 days, with the full first-notice-of-loss-to-final-payment stretch reaching 44 days, among the longest since the study launched in 2008. That number reflects what happens when a paper-based mortgagee workflow sits in the middle of a payment that could otherwise move.
Why does a mortgagee on the claim slow down contractor and claimant payment?
A mortgagee clause routes a claim payment through a second approval loop that has nothing to do with the claimant’s or contractor’s timeline. The lender has to confirm loan balance, verify escrow requirements, and endorse the check before funds move to repair. That loop was built around a paper instrument, and at most carriers it still runs that way.
Texas law shows how tightly this is regulated once it starts. An insurer there has five business days to mail a claim check after accepting the claim. The mortgage lender then has ten days to endorse it once the endorsement request arrives, with a 10% annual interest penalty if the lender holds past that window. The rule exists because lenders were holding. It also tells you something about the system: even with statutory deadlines on both sides, the check still has to physically travel to the lender, get signed, and travel back before a contractor sees a dollar.
That’s the structural problem. The claimant, the contractor, and the lender holding the mortgage aren’t really three separate payments. They’re three claims on the same check. And a check can only be in one place at a time.
What does a single disbursement instruction actually change?
A single disbursement instruction changes the unit of work. Instead of “one check, three signatures,” it becomes “one claim record, three independent payment legs.”
- Before: a single check had to travel physically between the lender and the payee, getting passed back and forth.
- Now: the claims system issues the disbursement instruction once.
- Then: the payment platform routes each portion to the party it belongs to, in whatever form that party can actually receive.
This is the mechanic behind the newer wave of lienholder integrations entering the market in 2025 and 2026. iink Payments, which partnered with claims platform Snapsheet in April 2025 specifically to remove paper from lienholder approval, described the gap directly. David Beck, business operations manager at Snapsheet, said iink “has identified an area of the claims process that a comprehensive tech-based solution has underrepresented.” He added that its approach “is truly mindful of all involved parties and keeps everyone tightly connected throughout the duration of the process.”
The same logic applies on the total-loss side. One Inc and vehicle auction company Copart integrated their systems in 2025 for paying off the lender that holds a lien on a written-off vehicle. Now a total-loss payment to that lender and the vehicle’s release to auction happen on the same timeline, instead of two separate ones. Ian Drysdale, CEO of One Inc, said the goal was to make sure “payments move quickly and accurately.” When lienholder payments clear faster, he explained, the asset moves faster too, “generating immediate value for insurers and minimizing disruptions for all involved.”
DisburseCloud’s approach to this problem runs through a partnership with LenderDock. LenderDock verifies the lender’s interest, confirms the loan balance, and checks escrow requirements in real time. That confirmation feeds directly into the disbursement instruction. When the criteria are met, the platform can skip the two-signature check entirely. It routes the claimant’s and contractor’s portions separately, while the lender’s share is confirmed and released against the same underlying claim record. Nobody waits on a signed envelope to come back before the next payment leg moves.
What would it take to cut the postage and check line in half by Q3?
Cutting a check-printing and postage budget in half by the third quarter is realistic when a carrier consolidates check runs into digital batches and retires the manual reconciliation steps built around paper. This isn’t a single technology swap. It’s a sequence.
- Consolidate check runs into scheduled digital batches, so payments that used to go out as one-off mailed checks move through a shared disbursement queue instead.
- Retire the manual reconciliation step where an adjuster or ops team matches a returned endorsed check against the claim file by hand.
- Route the mortgagee leg through automated verification, loan balance, escrow status, so it stops defaulting to a mailed two-party instrument.
- Redirect freed postage and print spend toward the payment infrastructure itself, rather than treating the savings as pure overhead reduction.
None of that requires replacing the system of record. It requires the claims system to issue one instruction and trust the payment layer to split it correctly, verify the lender in real time, and report back when each leg clears.
Why does payment speed matter more than payment size to claimants?
Speed moves satisfaction more than the size of the payment does. The gap is large. J.D. Power’s 2025 study found satisfaction scores of 777 out of 1,000 when policyholders rated communication with their insurer as “very easy.” That compares with just 337 when it was rated “difficult.” Claims resolved within ten days scored 167 points higher on satisfaction than those dragging past 31 days, per J.D. Power’s 2026 study.
That gap exists because most people don’t expect the process to be painless. They expect to know where the money is. InvoiceCloud’s 2025 Consumer Claims Experiences Survey found a wide gap between what claimants expect and what they get.
- 82% of customers expect payout within five days of filing.
- Only 10% actually received funds within hours to two days.
- 27% waited more than a week.
- 40% of respondents ranked payment speed as the single thing they’d most want changed about the process, ahead of communication quality.
The consequence of getting it wrong is not neutral: InvoiceCloud’s 2025 Consumer Claims Experiences Survey found a majority of consumers surveyed said they’d consider switching carriers after a poor claims experience.
What should a carrier check before automating mortgagee payments?
Before automating any lender-payment leg of a claim, a carrier should confirm that the lender data, loan balance, escrow status, active servicer, is verified against a current source, not a stale field pulled at policy inception. A verification layer that’s out of date defeats the purpose: it just moves the manual problem downstream, from a slow payment to a rejected one.
The regulatory backdrop is moving, not static. The National Association of Insurance Commissioners adopted a homeowners market data call at its Fall 2025 National Meeting covering eight years of claims data, due from insurers above a $50,000 premium threshold by June 2026. Carriers automating mortgagee payment flows now are building on ground that regulators are actively re-examining. That’s one more reason the verification step needs to be live, not cached.
FAQ
Does removing the two-party check eliminate the mortgagee’s legal right to review the claim?
No. Automating the payment leg confirms the lender’s loan balance and escrow position in real time rather than removing that check; it replaces the paper endorsement step, not the lender’s underlying interest in the property.
Can a contractor be paid before the mortgagee’s portion clears?
Yes. When the claim record splits into independent payment legs, the contractor’s and claimant’s portions can move on their own timeline instead of waiting on the mortgagee’s endorsement, provided the claim data supports separating the amounts.
What’s driving carriers to address this now rather than earlier?
Claim volume and payout pressure are both rising. Swiss Re Institute’s March 2026 report put 2025 global insured natural catastrophe losses at $107 billion. Secondary perils like severe convective storms and wildfire accounted for 92% of that total. That’s a volume that paper-based lender-payment workflows were never built to absorb.
Is instant payment the same fix as removing the manual hold?
No. Instant payment addresses how fast a single leg moves once released; the manual hold is a routing and verification problem that exists regardless of how quickly the check itself would clear.
The mortgagee clause was never the bottleneck. The paper instrument built around it was.
Separate the two, and three things follow:
- The claimant gets paid on their own timeline.
- The contractor gets paid on their own timeline.
- The lender gets paid on its own timeline.
All three run off the same claim record, no longer gated by the slowest party in the chain.